
Holiday Budget, Credit card balances in the United States hit 1.263 trillion dollars in the second quarter of 2026, according to the Federal Reserve Bank of New York, after households added another 21 billion dollars in just three months. The holiday season hasn’t even started yet, and the number that usually climbs fastest each year is already elevated. If you want this December to look different, September is actually the right time to start planning, not November.
What the Numbers Already Show
Recent surveys point to a pattern that repeats almost every year. About 44 percent of Americans expect to carry debt into 2027 from this year’s holiday spending, with the average amount carried sitting around 408 dollars per person. Multiplied across the country, that works out to roughly 48.6 billion dollars in post holiday debt.
Meanwhile, the average credit card interest rate is currently hovering around 20 percent. That detail matters more than people usually realize. A 400 dollar balance left unpaid at that rate doesn’t just sit there quietly. It grows every month it isn’t paid off, which is exactly how a manageable holiday splurge turns into a debt that follows you well past January.
Why This Year Is a Slightly More Expensive Year to Get Wrong
Two things make timing worse than usual this year if you end up carrying a balance. The Federal Reserve raised interest rates this month for the first time since 2023, and while credit card APRs don’t move in perfect lockstep with the Fed’s rate, they do tend to drift upward when it rises. On top of that, buy now pay later apps, which many people lean on during the holidays specifically because it feels lower risk than a credit card, come with their own late payment problem. Roughly 39 percent of shoppers plan to use BNPL this season, and recent data shows nearly half of BNPL users have paid late on one of these loans within the past year. None of that means avoid these tools completely. It just means going in with a plan matters more than usual.
A Simple Way to Build the Budget Now
The good news is that a holiday budget doesn’t need to be complicated, and starting now gives you roughly three months instead of three weeks to fund it.
Start with one number, not a list. Before you think about individual gifts, decide the total dollar amount you are comfortable spending across everything, gifts, travel, food, and decorations included. This single number matters more than any spreadsheet of individual prices.
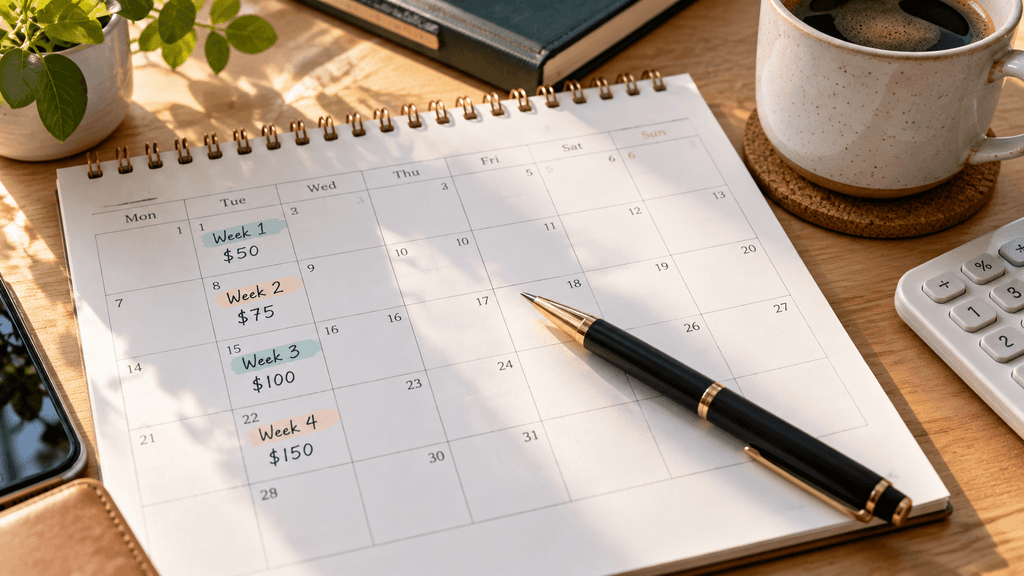
Divide it by the weeks you have left. If you land on a total of 600 dollars and there are twelve weeks until your shopping is done, that is 50 dollars a week to set aside, a much easier target to hit than trying to come up with the full amount in December. read more
Give the money somewhere to sit. Instead of leaving your holiday fund mixed in with everyday spending money, park it in a separate account, ideally one paying decent interest since you’ll be building the balance for a few months anyway. It won’t earn much over twelve weeks, but it keeps the money mentally separate from your regular budget, which tends to matter more than the interest itself.
Decide your payment method before you start shopping, not after. Paying with cash, debit, or a credit card you know you’ll pay off in full avoids interest entirely. If you do use BNPL for anything, keep it to one purchase on one platform so it’s easy to track, rather than stacking several plans across different apps at once listen to our complete podcast episodes covering this guide on podbean audio channel.
If You’re Starting Later Than You’d Like
If September planning isn’t realistic and you’re reading this in November instead, the same principles still work, just compressed. Pick the number first, prioritize the people and purchases that matter most, and give yourself permission to scale back the rest. A smaller, fully paid holiday season beats a bigger one you’re still paying off in April.
FAQ
How much holiday debt do Americans carry on average?
Recent surveys found the average American carries about 408 dollars in debt after the holidays, and roughly 44 percent expect to carry some amount of debt into the new year.
When should I start a holiday budget?
Ideally in September or October, giving yourself enough weeks to save gradually instead of covering the full cost in November and December alone.
Is it better to use a credit card or buy now pay later for holiday shopping?
Both carry risk if not managed carefully. A credit card paid in full avoids interest entirely, while buy now pay later avoids interest too but can lead to missed payments if spread across multiple apps at once. The safest option is cash or debit, or a credit card you’re confident you’ll pay off.
How much should I spend on the holidays this year?
There’s no universal number. Most surveys estimate average spending somewhere between 700 and 950 dollars per person, but the more useful approach is picking a total you’re comfortable with based on your own budget, not a national average.
What if I can’t afford my full holiday spending list?
Prioritize the people and purchases that matter most and scale back the rest. A smaller holiday season you pay for in full is a better outcome than a bigger one you’re still paying off months later.